If you are thinking about buying in Summerbrooke, you probably want more than pretty listing photos. You want to know how the process works, what to check before you commit, and how to avoid surprises once you are under contract. This step-by-step guide walks you through what to expect in Summerbrooke, from financing and HOA documents to inspections and post-closing paperwork. Let’s dive in.
Why buyers look at Summerbrooke
Summerbrooke is a planned-unit-development community in Mount Dora, and the City of Mount Dora lists Summerbrooke among its adopted PUD ordinances. According to Park Square Homes’ Summerbrooke community page, the neighborhood is about 2 miles from historic downtown Mount Dora.
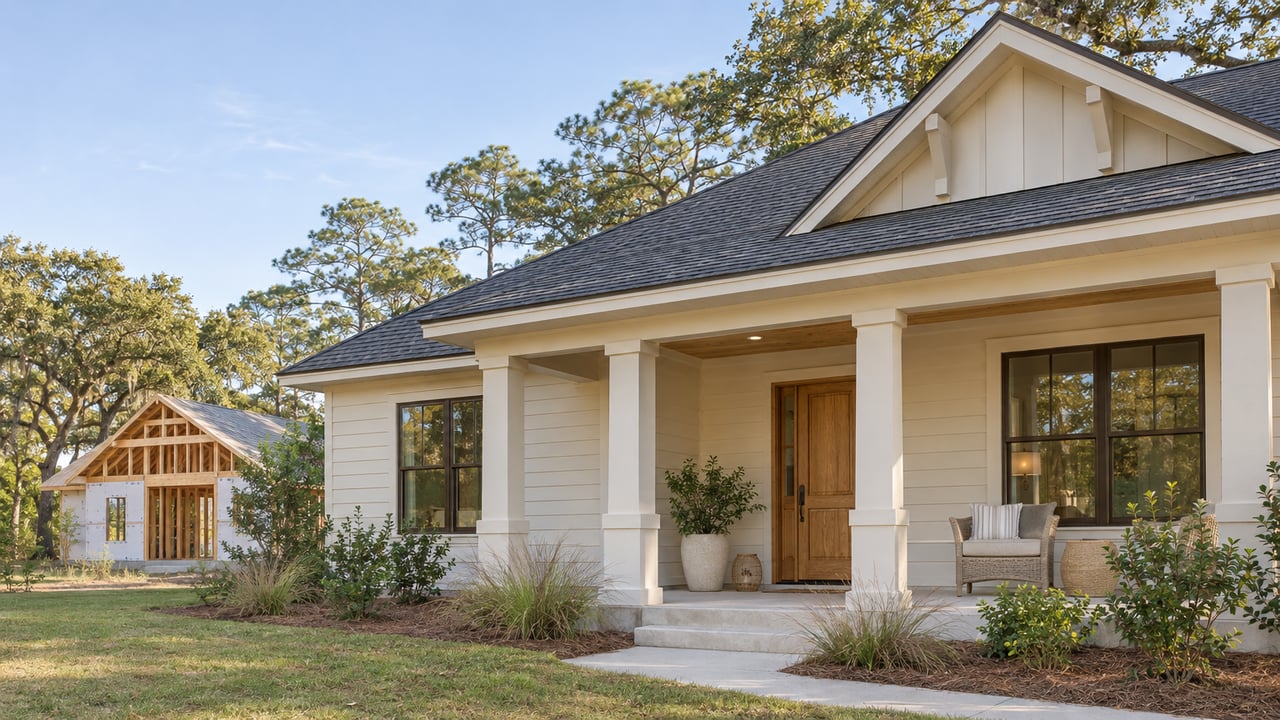
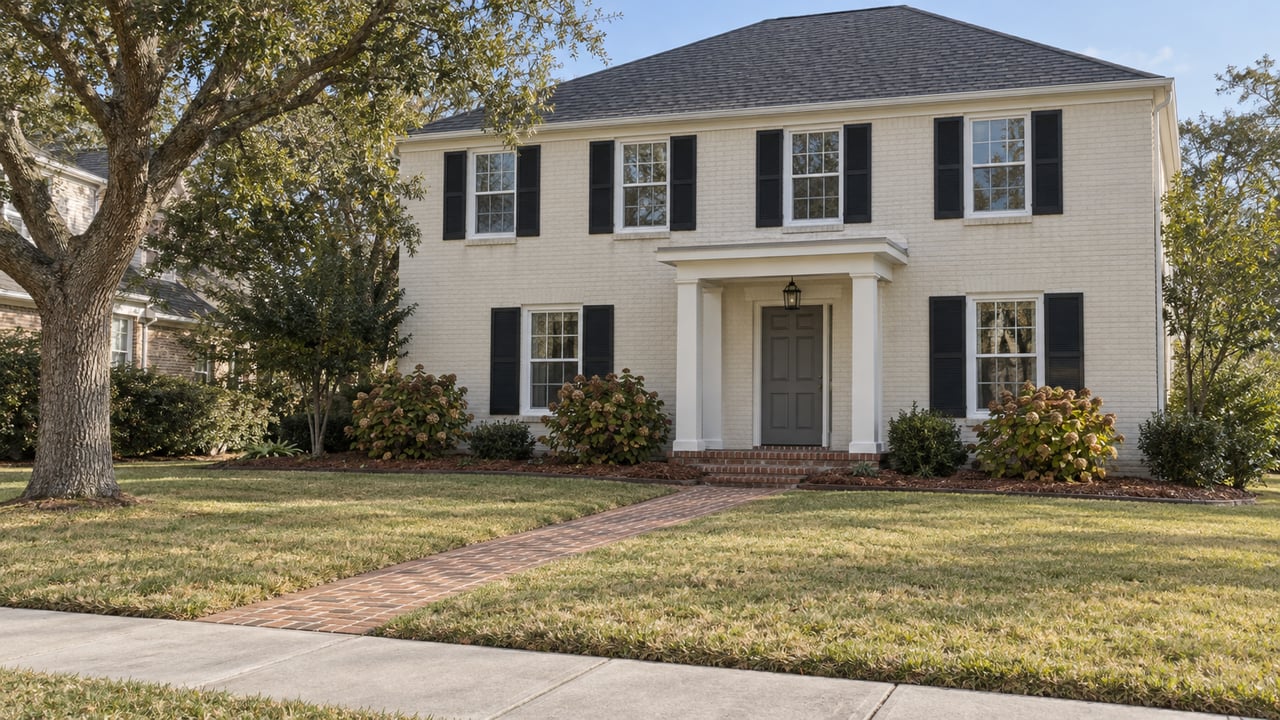
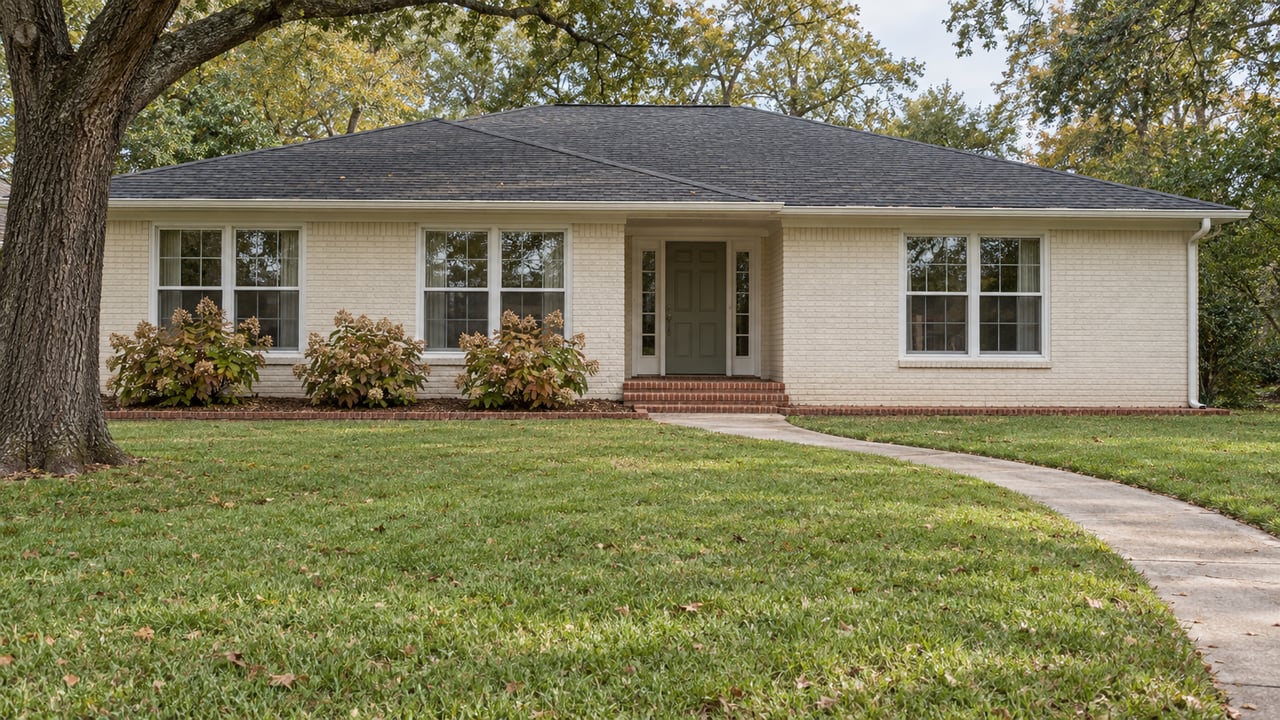
The builder currently markets eight floor plans ranging from 1,525 to 3,075 square feet, with starting prices from $399,990 to $515,990. Builder materials also highlight amenities such as a clubhouse, resort-style pool, walking trails, dog park, basketball court, fitness center, and recreation areas. If you want a newer home with shared amenities and access to Mount Dora, Summerbrooke may be worth a closer look.
Step 1: Get preapproved first
Before you schedule tours or compare floor plans, line up your financing. The Consumer Financial Protection Bureau explains that a preapproval letter is a tentative lender commitment, not a final guarantee, but sellers often want to see one before accepting an offer.
This is also the best time to set a realistic budget. The CFPB recommends reviewing your credit, gathering your paperwork, and preparing your application before you get serious about shopping. That small amount of prep can make the rest of your Summerbrooke search much smoother.
What to gather for preapproval
A lender will usually want a clear picture of your income, assets, and debts. Start organizing these items early:
- Preapproval letter
- Recent pay stubs
- W-2s or tax returns
- Bank and asset statements
- Debt list
- Gift-letter documentation, if applicable
If you are buying a new-construction home, it is also smart to ask whether any builder incentives depend on using a preferred lender or specific loan program.
Step 2: Understand the community setup
Summerbrooke is not just a collection of homes. It is an HOA-governed community, and that matters when you are comparing monthly ownership costs and day-to-day rules.
Recent listing data in the research report shows quarterly HOA dues around $301 to $310, or roughly $100 to $103 per month. Those same sources indicate the HOA fee covers shared items such as the pool, grounds, and recreational facilities, and at least one listing reports no CDD. Because listings can change, you should verify current fees, coverage, and any additional charges during your due diligence.
Questions to ask about the HOA
Ask for clear answers to these points before you move forward:
- What is the current quarterly HOA amount?
- What exactly does the fee cover?
- Is there any special assessment now or planned?
- Is there a transfer fee or capital contribution at closing?
- What are the pet, lease, and parking rules?
- Is HOA approval required?
- Is there any separate club or membership fee?
Based on the research, Summerbrooke’s value appears tied to its clubhouse and community amenities rather than a separate private club membership. Still, you should confirm that in the HOA packet before writing an offer.
Step 3: Request HOA documents early
In Florida, HOA documents are not a minor detail. They are a major part of your buying decision.
Under Florida law on HOA disclosure summaries, a prospective buyer in an HOA community must receive a disclosure summary before signing the contract. For Summerbrooke, you should go beyond the summary and review the full association package so you understand the financial and practical side of ownership.
HOA documents to review
Request these items as early as possible:
- Disclosure summary
- Declaration or CC&Rs
- Bylaws
- Rules and regulations
- Current budget
- Reserve information
- Special-assessment history
- Approval requirements
- Fee schedule
- Estoppel certificate request, if needed
Florida law also requires an estoppel certificate to be issued within 10 business days of the request when the association is handling closing arrears or dues verification. That timeline can affect your closing schedule, so it helps to stay ahead of it.
Step 4: Compare new construction and resale carefully
Summerbrooke may offer both builder inventory and resale opportunities, and the buying path can look different depending on which type of home you choose. That is why your offer terms should match the type of property you are buying.
For builder-led purchases, confirm the exact floor plan, homesite, included features, upgrade packages, and delivery timeline. The builder’s Summerbrooke page makes clear that buyers may be choosing among multiple floor plans and homesites, so details matter.
Key offer questions for Summerbrooke
If you are buying a new home, ask:
- Is the home move-in ready or to-be-built?
- Which upgrades are included in the price?
- Which features cost extra?
- Are there lot premiums?
- Do incentives depend on a preferred lender or loan type?
- What is the expected completion date?
If you are buying a resale, focus on the seller’s timeline, financing deadlines, and inspection period. You want your contract terms to fit both the property and the seller’s needs without leaving you rushed.
Step 5: Use inspections that fit Florida homes
Inspections are important in any purchase, but Florida homes often need a little extra attention. Your inspection plan should match the age, condition, and insurance needs of the property.
According to Citizens Property Insurance’s inspection guidance, a Florida-licensed inspector performs a four-point inspection on properties more than 20 years old, reviewing the roof, electrical, plumbing, and HVAC systems. Citizens also notes that a wind-mitigation inspection may document features that could qualify for insurance discounts.
Inspections to consider
Depending on the home, your file may include:
- General home inspection report
- Roof photos
- Four-point inspection, if the home is old enough
- Wind-mitigation inspection form
- WDO or termite report
The research report also notes that Florida requires wood-destroying organism inspection reports in certain real estate transaction scenarios when a fee is charged or a written report is requested. In practice, that makes termite and WDO checks especially relevant for many Florida buyers.
Step 6: Confirm utility and property details
Before closing, make sure you verify practical property details that affect ownership costs and future planning. Even in a newer community, you do not want to assume anything.
Current builder materials and listing references in the research report show public sewer, public water, and natural gas on some homes, and at least one current listing reports Flood Zone X. Those details can vary by lot or address, so confirm utility connections, flood-zone information, and insurance requirements for the exact home you plan to buy.
Step 7: Finish with closing and tax tasks
The finish line is not just signing papers. A good buying plan includes what happens right after closing too.
Keep your closing file organized with the title commitment, survey if ordered, closing disclosure, and proof of homeowners insurance. Then put one more date on your calendar: if the home will be your permanent residence as of January 1, Lake County says you may apply for homestead exemption by March 1.
That deadline matters because a homestead exemption can reduce assessed value significantly. It is one of the simplest ways to protect your budget after you buy.
Quick buyer checklist for Summerbrooke
Here is a simple way to stay organized as you move through the process:
- Get preapproved and set your budget
- Compare builder and resale options
- Ask for full HOA documents before committing
- Review fees, rules, and approval requirements
- Confirm whether any separate membership fee exists
- Match your offer terms to the type of home
- Order inspections that fit the property’s age and condition
- Verify utilities, flood zone, and insurance needs
- Keep closing documents in one place
- Apply for homestead exemption on time if eligible
School and location references
Community and listing data in the research report identify local school references as Triangle Elementary, Mount Dora Middle, and Mount Dora High. The report also notes that Lake County Schools reported the district as A-rated for 2024-25, and Mount Dora High was among the district-operated A-rated schools that year.
If school assignment is important to your move, verify current attendance boundaries and enrollment details directly during your home search, since assignments can change.
Buying in Summerbrooke can be a smart move when you go in with a clear plan. If you want help comparing homes, reviewing community details, and keeping each step on track, connect with The Tagoe Team for straightforward guidance and responsive support.
FAQs
What is Summerbrooke in Mount Dora, Florida?
- Summerbrooke is a planned-unit-development community in Mount Dora with new-home offerings, shared amenities, and an HOA-governed setup.
What amenities are available in Summerbrooke?
- Builder materials list a clubhouse, resort-style pool, walking trails, dog park, basketball court, fitness center, and recreation areas.
What should buyers review in Summerbrooke HOA documents?
- You should review the disclosure summary, declaration, bylaws, rules, budget, reserve information, special-assessment history, approval requirements, fee schedule, and any estoppel-related details.
What inspections should buyers consider for a Summerbrooke home?
- Buyers should typically consider a general inspection, and depending on the home, may also need a four-point inspection, wind-mitigation inspection, roof documentation, and a WDO or termite report.
When should a Lake County buyer apply for homestead exemption?
- If the home is your permanent residence as of January 1, you may apply for homestead exemption by March 1 according to Lake County.